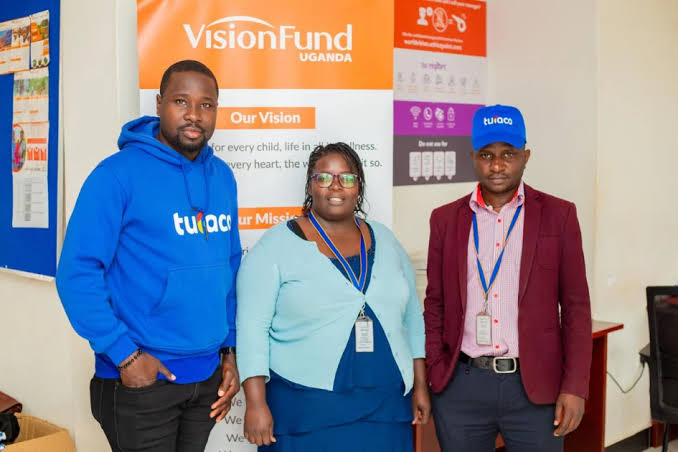
When Turaco and VisionFund International formalised their global partnership through a Memorandum of Understanding earlier this year, the announcement carried weight beyond a standard commercial agreement. At its core, the deal addresses one of the most persistent structural gaps in West African and broader African financial governance: the near-total exclusion of low-income households from formal risk-management mechanisms. Roughly 250,000 people in Kenya and Uganda are already covered under the two organisations’ existing collaboration, and that figure now serves as the baseline from which an ambitious continental scaling effort will be launched.
The architecture of the partnership is deliberate. VisionFund International, the microfinance arm of World Vision, brings an established network of microfinance institutions with deep community-level trust. Turaco, a technology-driven microinsurance provider, contributes product design and distribution infrastructure calibrated for low-income markets. Together, they are attempting to solve a market-failure problem that neither regulation nor philanthropy has resolved on its own: insurance penetration rates across sub-Saharan Africa remain below 3 percent of GDP, compared to a global average exceeding 6 percent, leaving the majority of African households to absorb economic shocks through savings depletion, asset liquidation, or debt accumulation.
The MOU extends the collaboration beyond Kenya and Uganda, identifying Tanzania, Ghana, Zambia, and Rwanda as the first wave of expansion markets. Ghana’s inclusion is particularly significant from a West African governance perspective. As ECOWAS’s second-largest economy and a country that has spent the past two years navigating a sovereign debt restructuring under an IMF programme, Ghana represents both the opportunity and the urgency of building household-level financial resilience. When national fiscal buffers collapse, the social cost falls disproportionately on low-income families who hold no insurance and no formal savings instruments capable of absorbing illness, death, or disability-related income loss.
The mechanism through which the partnership operates is worth examining closely. Rather than building standalone insurance distribution channels, Turaco and VisionFund will embed insurance products directly into the microfinance loans and savings products that VisionFund’s institutions already distribute. This bundling approach addresses a fundamental adoption barrier: low-income households in markets like Ghana and Uganda do not distrust insurance as a concept so much as they distrust unfamiliar institutions and opaque claims processes. By anchoring insurance to a financial relationship that already exists, the model bypasses the customer acquisition problem that has historically made microinsurance commercially unviable at scale.
The planned product expansion into preventive and outpatient healthcare coverage signals a further evolution in thinking about what microinsurance can accomplish institutionally. Conventional microinsurance products across the continent have concentrated on life and credit-life coverage, largely because mortality is a binary, verifiable trigger that minimises claims disputes. Outpatient coverage, by contrast, requires functioning healthcare provider networks, claims verification infrastructure, and pricing discipline in markets where healthcare costs are poorly documented. That Turaco and VisionFund are moving in this direction suggests a degree of operational confidence grounded in the data generated through their Kenya and Uganda programmes.
VisionFund’s experience in Latin America and Asia will inform product development across African markets, according to the agreement. This cross-regional knowledge transfer matters because it repositions the partnership as a learning institution rather than a simple replication exercise. Markets like Peru and the Philippines, where VisionFund operates, have developed microinsurance regulatory frameworks and provider ecosystems that African regulators have studied but rarely adapted with sufficient specificity. The explicit commitment to draw on that experience suggests the partnership intends to engage African insurance regulators, including Ghana’s National Insurance Commission and Tanzania’s Tanzania Insurance Regulatory Authority, as co-architects of the expansion rather than as compliance checkboxes.
From a regional integration standpoint, the partnership’s design raises a productive question for ECOWAS financial governance: why does microinsurance scaling still depend on bilateral country-by-country partnerships rather than on a regional regulatory framework that would allow licensed providers to operate across member states? WAEMU countries, which share a common central bank and a partially harmonised financial regulatory architecture, have made incremental progress on cross-border financial service provision, but insurance remains largely outside that harmonisation effort. A partnership of this scale, operating simultaneously in Ghana, Tanzania, Zambia, and Rwanda, will generate comparative data on product uptake, claims ratios, and regulatory friction that could inform exactly the kind of evidence-based regional policy reform that ECOWAS’s financial integration agenda requires.
The investor and development-finance dimension of the partnership also deserves scrutiny. Turaco has previously raised capital from impact investors and development finance institutions, and VisionFund operates within World Vision’s broader development mandate. The combination creates a hybrid financing structure where commercial sustainability and social impact objectives must be continuously reconciled. In markets like Ghana, where the cedi’s depreciation has eroded household purchasing power significantly since 2022, pricing insurance premiums at levels that are both affordable and actuarially sound is a genuine technical challenge, not merely a marketing problem. Premium affordability in local currency terms, claims payment reliability, and regulatory capital requirements will determine whether the model achieves the scale its architects envision or remains a well-intentioned programme serving a fraction of its target population.
Ted Pantone, Turaco’s CEO and Co-Founder, framed the expansion as a continuation of what the Kenya and Uganda experience demonstrated: that insurance embedded in trusted financial products generates meaningful uptake among households that would never seek out a standalone insurance product. Edgar Martinez, VisionFund International’s CEO, positioned the global partnership as a vehicle for reaching families before crisis strikes rather than after, a framing that aligns with a preventive rather than remedial approach to financial inclusion. Both framings are credible, but they will be tested against the operational realities of markets with weaker healthcare infrastructure, less mature credit bureau systems, and more volatile macroeconomic environments than Kenya.
What the Turaco-VisionFund partnership ultimately represents is a structured attempt to build a private-sector microinsurance infrastructure in the absence of adequate state provision. Across West Africa, public social protection systems cover a small fraction of informal-sector workers, who constitute the majority of the labour force in Ghana, Senegal, and Nigeria alike. The AfCFTA’s ambition to deepen intra-African trade and investment flows depends, at the household level, on economic actors who can absorb shocks without catastrophic asset loss. A microinsurance architecture that reaches scale in Ghana and Tanzania over the next five years would not merely serve its direct beneficiaries; it would constitute a form of institutional infrastructure that supports the broader conditions under which regional economic integration becomes meaningful for ordinary households rather than only for formal enterprises and capital markets. Whether the partnership delivers on that potential will depend on regulatory engagement, pricing discipline, and the willingness of African insurance authorities to treat microinsurance not as a marginal product category but as a core instrument of financial governance.