What exactly is Fuliza Ya Pochi, and who does it serve?
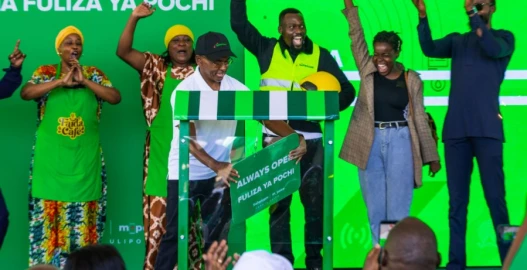
On 22 October 2026, Safaricom launched Fuliza Ya Pochi at Makongeni Market in Thika, extending overdraft credit directly to micro-merchants operating through its Pochi La Biashara digital wallet. The product is not a loan in the conventional sense: it is an automated overdraft facility that activates when a merchant’s Pochi wallet balance falls below zero, allowing the business to complete transactions, pay suppliers, purchase inventory, send money, and settle utility bills without interruption. Repayment is automatic, deducted from the next inflow of customer payments into the wallet. The mechanism is elegant in its simplicity, and deliberately so.
Eligibility is tied to demonstrated business activity. Merchants must have used Pochi La Biashara for more than six months, and the credit ceiling assigned to each account reflects the volume and regularity of transactions recorded on the platform. Safaricom Group CEO Peter Ndegwa confirmed that the facility targets the platform’s 3.3 million registered Pochi customers, drawing a direct parallel to the individual Fuliza overdraft product, which currently serves 17 million personal M-Pesa users. The service is accessible through the Pochi Mini App on Safaricom’s My OneApp or via the USSD code *334#, a design choice that keeps the product reachable for merchants who operate on basic handsets.
Why does working capital access matter so acutely for micro-merchants?
The structural credit gap facing micro and small enterprises across sub-Saharan Africa is well-documented. Informal traders, market vendors, and small-scale merchants typically operate on daily or weekly revenue cycles, purchasing stock from suppliers in cash, collecting revenue in small denominations, and managing thin margins that leave almost no buffer against demand fluctuations or delayed payments. When a wallet balance hits zero mid-transaction, a sale is lost, a supplier relationship is strained, or a utility payment is missed. These are not abstract inconveniences: for a trader like Grace Wambui, who welcomed the launch at Makongeni Market and cited the ability to restock as a direct benefit, the difference between having and not having a GHS 500 or Ksh 2,000 credit line can determine whether a business survives a slow week.
Formal banking institutions have historically failed to serve this segment. Collateral requirements, minimum account balances, lengthy credit assessment processes, and branch-based service models exclude the overwhelming majority of micro-merchants across East and West Africa alike. Digital credit, anchored in transaction data rather than physical collateral, represents a structurally different approach to underwriting risk, one that Safaricom has refined progressively since introducing the original Fuliza overdraft in 2019 and subsequently rolling out Fuliza ya Biashara for Lipa na M-Pesa merchants.
How does this fit within Safaricom’s broader digital financial architecture?
Fuliza Ya Pochi is not an isolated product launch. It is the latest layer in a financial infrastructure that Safaricom has assembled over nearly two decades, with M-Pesa as its foundational payment rail. Pochi La Biashara, which currently serves more than two million micro-merchants, was itself a governance innovation: it separated business revenue from personal funds within the same mobile money ecosystem, giving merchants a rudimentary but functional form of business account without requiring a bank relationship. Fuliza Ya Pochi now adds a credit dimension to that account, transforming Pochi from a passive wallet into an active working capital instrument.
The sequencing matters analytically. Safaricom introduced zero transaction charges on customer payments of up to Ksh 200, alongside a 50 per cent reduction in charges on payments above Ksh 200, capped at Ksh 50, for a three-month period. Reducing friction costs while simultaneously introducing credit access represents a coordinated effort to deepen merchant dependency on the Pochi ecosystem, increasing platform stickiness and generating richer transaction data that can refine future credit assessments. The business logic is straightforward: a merchant who uses Pochi to receive payments, manage expenses, access credit, and pay suppliers has little incentive to migrate to a competing platform.
The role of transaction data in credit underwriting
The underwriting model underpinning Fuliza Ya Pochi deserves particular attention from a governance and regulatory standpoint. Credit limits are determined algorithmically, based on business activity recorded within the Pochi ecosystem. This approach bypasses traditional credit bureau infrastructure, which remains underdeveloped across much of East Africa, and instead treats the merchant’s own payment history as a proxy for creditworthiness. The model is efficient and scalable, but it also raises questions about data ownership, transparency of scoring criteria, and the recourse available to merchants who believe their credit limits are set incorrectly. Regulatory frameworks governing digital credit in Kenya, administered by the Central Bank of Kenya under the 2021 Digital Credit Providers Regulations, require disclosure of pricing and credit terms, but the opacity of algorithmic scoring remains a live governance debate across the region.
What are the regional governance and integration implications?
Kenya’s mobile money ecosystem is among the most mature on the continent, and Safaricom’s successive product innovations have consistently set reference points for regulators and competitors across East and West Africa. The Fuliza model, in particular, has attracted attention from fintech operators and central banks in Nigeria, Ghana, and Senegal, where mobile money penetration is growing rapidly but the credit overlay remains underdeveloped. In Ghana, MTN Mobile Money and Vodafone Cash serve millions of registered users, yet overdraft-style credit products tied to merchant wallets remain nascent, partly because the regulatory environment for digital credit has been slower to crystallize than in Kenya.
Within the ECOWAS framework, the question of how digital financial services regulation should be harmonized across member states is increasingly pressing. The West African Monetary Institute, tasked with preparing the groundwork for a common West African currency, has identified financial inclusion and digital payment infrastructure as prerequisites for monetary convergence. A fragmented regulatory landscape, in which each national central bank sets its own rules for digital credit providers, creates compliance costs for regional operators and limits the ability of successful models like Fuliza to scale across borders without significant structural adaptation.
The AfCFTA’s digital trade protocol, still under negotiation, adds another dimension. If cross-border digital financial services are to become a meaningful component of intra-African trade, the governance architecture governing credit products, data portability, and consumer protection will need to be built at the regional level, not assembled piecemeal by individual regulators responding to domestic pressures. Kenya’s experience with Fuliza, including its documented tensions around over-indebtedness among low-income users of the personal product, offers a cautionary dataset that West African regulators would be well-served to study before their own ecosystems reach comparable scale.
What should regulators and institutions prioritize?
The Fuliza Ya Pochi launch surfaces a set of concrete institutional questions that extend well beyond Kenya. For regulators across the region, the immediate priority is establishing transparent disclosure standards for algorithmic credit products, ensuring that merchants understand the cost of credit, the basis on which limits are set, and the mechanism by which disputes can be resolved. The Central Bank of Kenya’s 2021 framework provides a partial template, but its enforcement record and its applicability to embedded credit products within payment platforms rather than standalone lending apps remain areas of active scrutiny.
For ECOWAS institutions and the AU’s African Financial Stability Mechanism, the broader task is building a regional regulatory sandbox that allows digital credit innovations to be tested across borders under coordinated oversight, rather than forcing each national regulator to respond independently to products that are inherently cross-border in their architecture. Safaricom’s own regional expansion through M-Pesa, already operational in multiple East African markets, demonstrates that mobile money platforms do not respect national boundaries in their commercial logic, even when regulatory frameworks remain firmly national in their jurisdiction.
Peter Ndegwa’s stated ambition, to replicate for 3.3 million Pochi merchants what Fuliza has achieved for 17 million individual users, is a measurable benchmark. Whether Fuliza Ya Pochi delivers on that ambition without reproducing the debt-cycle risks observed in the personal Fuliza product will depend as much on the quality of regulatory oversight as on the sophistication of Safaricom’s own credit models. That is the governance test that matters.