Investor interest, however prominent, means little without institutional follow-through. That is the core governance challenge now facing the Ghana Investment Promotion Authority as it attempts to convert Aliko Dangote’s publicly stated interest in Ghana’s sugar and cocoa processing sectors into structured, contractual investment reality.
From Declaration to Deal: The Institutional Mechanics at Stake
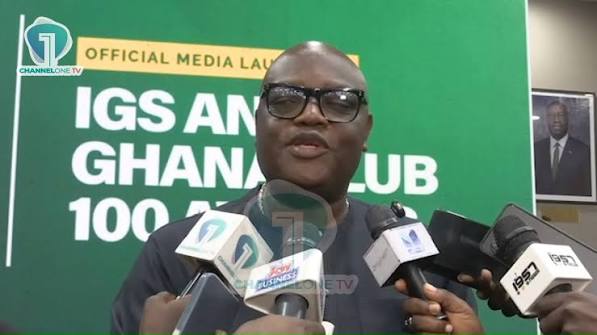
Simon Madjie, Chief Executive Officer of GIPA, confirmed at the Invest Ghana Summit 2026 in Accra that his authority would actively pursue Dangote’s proposals rather than wait for the billionaire industrialist to return with a formal plan. “He spoke about going into the sugar industry in Ghana. He spoke about going into the cocoa processing industry in Ghana. So we’ll seek to follow up to see that those proposals come to fruition,” Madjie said. The distinction between a public declaration of intent and a signed investment agreement is precisely where many high-profile African investment announcements have historically collapsed, and GIPA’s decision to take an active facilitation posture signals an awareness of that institutional gap.
What makes this particular case consequential is the identity of the investor. Dangote Group is not a speculative foreign fund; it is the continent’s most recognisable industrial conglomerate, with operational footprints in cement, fertiliser, and petroleum refining across multiple African markets. Its entry into Ghana’s sugar sector would directly challenge the country’s chronic dependence on imported refined sugar, a structural vulnerability that costs Ghana hundreds of millions of US dollars annually in foreign exchange outflows. Similarly, deepening cocoa processing capacity, rather than exporting raw beans, has been a stated priority of successive Ghanaian governments for decades, yet value addition within the country remains stubbornly low relative to the volume of raw cocoa Ghana produces as the world’s second-largest producer.
Cocoa and Sugar: Two Sectors, One Structural Argument
Ghana’s cocoa sector illustrates the governance tension between commodity dependence and industrial ambition with particular clarity. The country exports approximately 700,000 to 800,000 metric tonnes of cocoa beans annually, yet domestic processing captures only a fraction of the value chain before those beans are transformed into chocolate in European and North American factories. The Ghana Cocoa Board, known as COCOBOD, maintains tight regulatory control over the sector, and any large-scale processing investment by a private actor of Dangote’s scale would require careful negotiation of that regulatory architecture. GIPA’s facilitation role is therefore not merely logistical; it is fundamentally about regulatory alignment and institutional coordination between the investment authority, COCOBOD, and the Ministry of Food and Agriculture.
The sugar sector presents a different but equally instructive governance picture. Ghana currently has limited domestic sugar production capacity, with the Komenda Sugar Factory representing a long-troubled attempt to build local refining infrastructure. That project’s difficulties, marked by financing gaps, logistical constraints, and inconsistent government support over multiple administrations, serve as a cautionary precedent. A Dangote investment in sugar would need to navigate land access, water rights, power supply reliability, and offtake agreements in a policy environment that has not always provided the regulatory consistency that large-scale agro-industrial investors require. Whether GIPA can coordinate across those ministries and agencies with sufficient coherence to make the investment viable is the operative institutional question.
Regional Significance: What Dangote’s Ghana Pivot Means for West African Integration
Dangote’s interest in Ghana carries weight beyond bilateral investment promotion. Within the ECOWAS free trade architecture and the broader AfCFTA framework, an industrial operation producing refined sugar or processed cocoa derivatives in Ghana would have natural incentives to supply regional markets. Ghana’s geographic position, its port infrastructure at Tema, and its relatively stable macroeconomic trajectory compared to Nigeria, where Dangote’s core operations are based, make it a plausible regional processing hub. Nigeria’s naira volatility and fuel subsidy legacy costs have complicated the operating environment for even Dangote’s domestic businesses, lending credibility to a diversification strategy that plants industrial capacity in a neighbouring Anglophone economy with its own currency dynamics.
For ECOWAS’s broader ambitions around intra-regional trade, which currently sits at a deeply inadequate 15 to 20 percent of total member-state trade volumes, a major cross-border industrial investment of this nature would represent a meaningful proof of concept. It would demonstrate that the bloc’s investment protocols and trade facilitation instruments can support genuine productive integration rather than merely tariff negotiations on paper. Ivory Coast, Ghana’s immediate western neighbour and its most direct competitor for cocoa-sector investment, will be watching the GIPA facilitation process closely. Abidjan has invested heavily in positioning itself as the region’s premier agro-industrial hub, and a successful Dangote-Ghana partnership in cocoa processing would directly contest that positioning.
GIPA’s Institutional Credibility and the 2027 Independence Milestone
Beyond the Dangote file, Madjie outlined a broader institutional ambition: establishing a permanent, country-branded annual investment summit that would bring international capital allocators physically into Ghana to assess opportunities firsthand. “Instead of engaging investors outside the country all the time, at some point, we have to invite those who are close to taking investment decisions to come into our country, look at the opportunities we have,” he said, framing Ghana’s 70th independence anniversary in 2027 as a strategic inflection point for upgrading the country’s investment promotion architecture.
The logic is sound, and comparable models exist. Rwanda’s Transform Africa Summit and Senegal’s Dakar Business Forum have demonstrated that country-branded investment events, when backed by genuine regulatory reform and credible deal pipelines, can shift investor perception and generate measurable FDI commitments. Ghana’s version of this model will succeed or fail on the same criteria: the quality of the investment climate it presents, the reliability of its regulatory institutions, and the ability of GIPA itself to function as a genuine one-stop facilitation body rather than a ceremonial gateway. The authority’s handling of the Dangote proposals will be an early and visible test of that capacity.
The institutional challenge GIPA faces is not one of ambition but of execution. Translating a billionaire’s summit remarks into a functioning sugar refinery or cocoa processing plant requires sustained inter-agency coordination, transparent land and licensing processes, and the kind of regulatory predictability that Ghana’s investment environment has not always delivered consistently. If GIPA can demonstrate that it has the mandate, the inter-ministerial authority, and the technical capacity to shepherd a complex agro-industrial investment from expression of interest to operational project, it will have made a concrete contribution to Ghana’s industrial development strategy and to the credibility of West African investment promotion institutions more broadly.