Ghana’s domestic aviation sector operates under structural conditions that systematically suppress fare competition, with policy choices made over the past decade narrowing the market to two scheduled carriers and leaving consumers with limited alternatives.
From Four Carriers to Two
The contraction began in 2013. At that point, Ghana’s domestic routes hosted four active operators: Starbow, Citylink, Fly540, and Africa World Airlines (AWA). That configuration, while modest by regional standards, sustained a degree of competitive pressure sufficient to incentivize fare differentiation and route expansion.
By 2017, the market had collapsed to a single operator. The exits of Starbow, Citylink, and Fly540 were not simultaneous, but their cumulative effect was decisive. AWA held the domestic market alone for roughly a year before PassionAir entered in 2018, restoring a duopoly that has since remained unchanged.
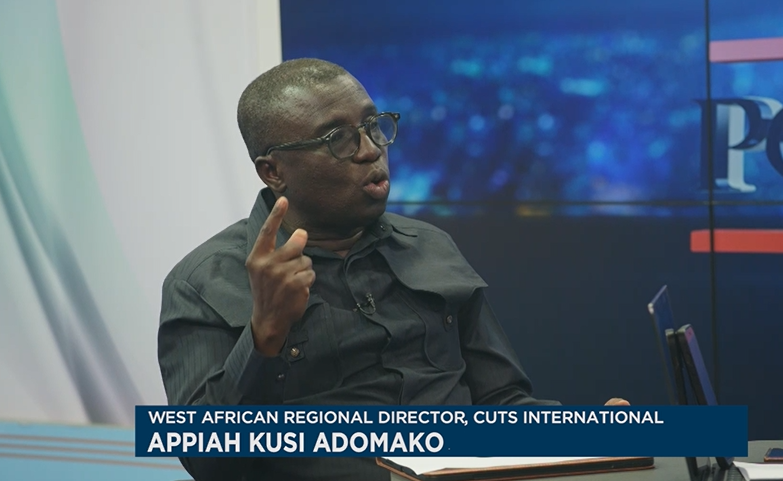
Appiah Kusi Adomako, West Africa Regional Director of CUTS International, a consumer and trade policy research organization, documented this trajectory in an analysis of the structural drivers behind Ghana’s elevated domestic airfares. His findings position market concentration not as an incidental outcome, but as a governance and regulatory failure with direct consequences for consumers and economic connectivity.
The Mechanics of Reduced Competitive Pressure
Adomako’s analysis does not allege misconduct by AWA or PassionAir. His argument operates at the structural level: when the number of independent competitors falls, the incentive architecture that drives pricing discipline weakens, regardless of whether remaining operators coordinate. “Two airlines do not prove collusion or abuse,” he wrote, “but fewer independent rivals reduce the pressure to discount, innovate and pursue marginal passengers.”
This distinction matters for regulatory purposes. A market with two carriers can produce high fares through parallel behavior rather than explicit coordination, a dynamic that competition authorities find difficult to prosecute but that produces identical consumer harm. Ghana’s Fair Wages and Salaries Commission and the newly reconstituted Ghana Competition Authority face precisely this analytical challenge: identifying when market structure, rather than conduct, is the primary policy problem.
The regional comparison sharpens the concern. Côte d’Ivoire, Ghana’s principal economic competitor in the Gulf of Guinea, has similarly thin domestic aviation coverage, but benefits from stronger connectivity to Abidjan’s international hub and WAEMU-integrated transport infrastructure. Nigeria, operating at a different scale, sustains five to six domestic carriers across its trunk routes, producing fare variability that, while still high by global standards, reflects genuine price competition on Lagos-Abuja and Lagos-Port Harcourt corridors. Senegal has pursued a different model, anchoring regional connectivity through Air Senegal’s expansion strategy rather than domestic route density.
Regulatory Conditions and Market Entry Barriers
The structural question is what prevented new entrants from filling the gap left by Starbow and Citylink. Aviation markets are capital-intensive and operationally complex, but regulatory conditions determine whether those barriers are navigable or prohibitive. Ghana’s aviation licensing framework, slot allocation procedures at Kotoka International Airport, and access to maintenance, repair, and overhaul (MRO) infrastructure all shape the cost calculus for prospective entrants.
Low-cost carrier (LCC) models, which have transformed domestic aviation markets in East Africa through operators like Jambojet and RwandAir’s regional expansion, depend on lean operational costs, high aircraft utilization, and predictable regulatory treatment. Where licensing timelines are long, slot access is opaque, or fuel supply chains carry embedded inefficiencies, LCC unit economics deteriorate before a single ticket is sold.
Adomako explicitly called on the Ghanaian government to create regulatory conditions that lower entry barriers for new carriers, with particular emphasis on low-cost operators.
Implications for Regional Connectivity and AfCFTA Integration
Ghana’s domestic fare structure carries implications that extend beyond consumer welfare on the Accra-Kumasi or Accra-Tamale routes. Under the African Continental Free Trade Area (AfCFTA), whose Secretariat is headquartered in Accra, Ghana has positioned itself as a gateway economy for West African trade facilitation. High domestic airfares raise the cost of business travel, constrain the movement of skilled labor, and increase logistics costs for time-sensitive goods, each of which directly undermines the competitiveness that AfCFTA integration is designed to generate.
ECOWAS’s Yamoussoukro Decision, the continent’s principal framework for liberalizing intra-African air transport, commits member states to open skies, fifth freedom rights, and the elimination of restrictions on intra-regional routes. Ghana is a signatory. The gap between that commitment and the domestic market’s structural reality reflects a broader implementation deficit that has characterized the Yamoussoukro framework since its adoption in 1999: formal legal obligations that member state regulatory agencies have not operationalized into market-opening practice.
For investors assessing Ghana’s logistics infrastructure, the aviation market’s concentration signals a regulatory environment that has struggled to sustain competitive market structures in capital-intensive sectors. That signal carries weight beyond aviation, touching on how Ghana manages competition policy in telecoms, financial services, and energy, all sectors where incumbent advantages can entrench without active regulatory intervention.
The Path to a Functioning Domestic Market
Restoring competitive dynamics to Ghana’s domestic aviation market requires the Ghana Civil Aviation Authority and the Ministry of Transport to treat market structure as an active policy variable, not a passive outcome. The entry of a third scheduled carrier, ideally structured on an LCC model, would alter the pricing environment measurably. Evidence from markets that moved from duopoly to three-carrier competition, including several East African corridors during the 2010s, consistently shows fare reductions of 15 to 30 percent on affected routes within 18 months of new entry.
The institutional capacity to drive that outcome exists within Ghana’s regulatory framework. What the evidence from the past decade suggests is that it has not been consistently deployed. Reversing the contraction that began in 2013 is a governance task as much as a market one, and the tools available to Accra are regulatory, not rhetorical.